
From a $5 pack at the counter to a high-value graded card online, your payment setup should be ready for the way collectors actually buy.
USA Payments helps card and hobby shops accept payments in-store, online and at events with POS options, card‑not‑present processing, fraud tools and support for higher-ticket transactions.
Support payments across the counter, your own website and other channels you control.
Build the processing setup around the transaction sizes your shop actually handles.
Add tools designed to help identify suspicious transactions and manage payment disputes.
Evaluate payment and POS options around the way your shop already operates.
01
A customer may buy a single booster pack over the counter.
02
Another may spend hundreds on a sealed hobby box.
03
Someone online may buy a graded card worth several thousand dollars.
04
The shop may take hundreds of transactions during a major release.
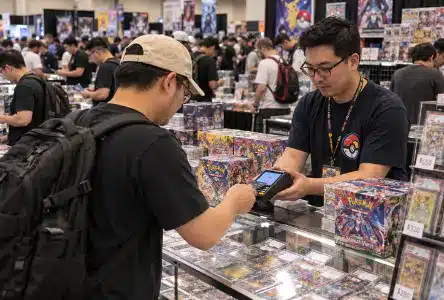
05
Then the team packs up and sells from a table at a card show that weekend.
That is not a typical retail payment environment.
Card and hobby shops may sell:
Trading card singles
Sealed TCG products
Sports cards
Graded cards
Memorabilia
Collectibles
Board games
Comics
Accessories
Event registrations
Other hobby products
And those sales may happen in-store, online, at shows or through other supported channels.
USA Payments starts with how the shop actually sells.
Then we look at the payment setup that fits it.
The counter is still a major part of the card-shop experience. Customers want to tap, insert or swipe and get back to the cards.
But the payment system also has to fit the way the shop operates.
Depending on the business, USA Payments can evaluate:
Countertop terminals
Mobile payment devices
Supported POS systems
Contactless payments
Digital wallets
Other in-person payment options
If you already have a POS or shop-management system, we start there.
The goal is not to replace working software just because we can.
It is to determine whether the payment side fits the shop.
A growing card business rarely exists only at the counter.
You may sell through:
Your own ecommerce store
Payment links
Invoices
Phone orders
Live-selling workflows
Other supported online channels
When the physical card is not presented during the transaction, the payment generally falls into the card‑not‑present environment.
That distinction can matter for fraud, chargebacks and processing costs.
It becomes even more important when the item being shipped is rare, expensive or difficult to replace.
USA Payments can help build the CNP side of the payment setup around what your card or hobby shop actually sells.
A card show can put a very different demand on the payment setup than an ordinary day in the store.
You may have:
Larger-than-normal ticket sizes
More transactions in a shorter window
Customers you have never dealt with before
Limited connectivity
Mobile checkout needs
Inventory moving quickly across the table
USA Payments can evaluate mobile and card-present payment options for shows, conventions and other in-person events.
Your payment setup should travel with the business when the inventory does.
Not every card-shop transaction is a $20 sale.
Graded cards, rare singles, sealed product and memorabilia can create transaction values far above ordinary retail. That changes the payment conversation.
Two questions become especially important:
USA Payments looks at the shop’s average and maximum ticket during the payment review so higher-value transactions are part of the conversation from the beginning.
Depending on the sale, alternative payment options such as ACH or Pay by Bank may also be worth evaluating.
A chargeback on a $20 retail item is frustrating. A dispute involving a $5,000 graded card is a different problem.
Card and hobby businesses can face disputes involving:
Unauthorized transactions
Item condition
Delivery
Authenticity
Refunds
Transaction recognition
High-value purchases
Card-not-present fraud
The processor cannot eliminate that risk.
But the payment setup should account for it.
USA Payments can help evaluate fraud tools, transaction controls and chargeback-management options appropriate for the way the shop sells.
Clear policies, accurate transaction records and good fulfillment documentation matter too.
The more valuable the item, the more important the transaction becomes before you click “approve.”
Card-shop volume is not always predictable.
1
A major product release drops.
2
A new Pokémon or sports-card set arrives.
3
A live sale takes off.
4
The shop attends a major convention.
5
A high-value collection comes through the door.
Suddenly the transaction volume or average ticket looks very different from an ordinary week.
That is not necessarily a problem.
But the processing account should be built with the actual business in mind.
USA Payments looks at normal volume, expected peaks and larger-ticket activity before recommending a setup.
If the business is growing or the transaction pattern is changing, tell us before the processor has to figure it out from the statement.
A good sales week should look like growth to your processor, not a mystery.
The hobby is bigger than one type of store. USA Payments works with businesses such as:
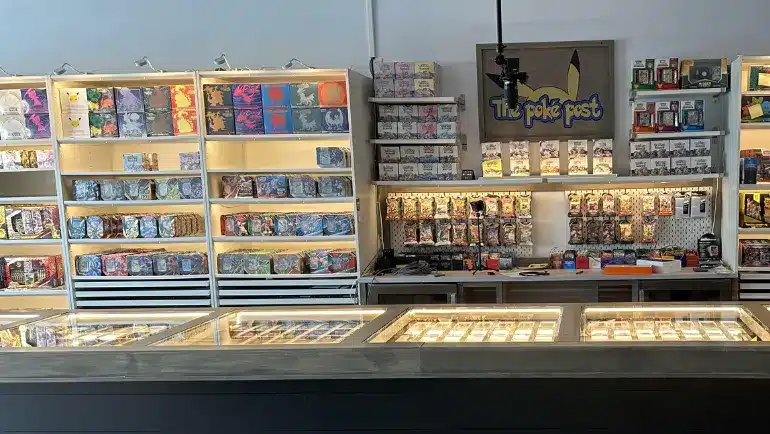
Payment processing for shops selling singles, sealed products, accessories, events and other trading-card inventory.
Support for in-store, online and higher-ticket sales involving raw cards, graded cards, sealed wax and memorabilia.
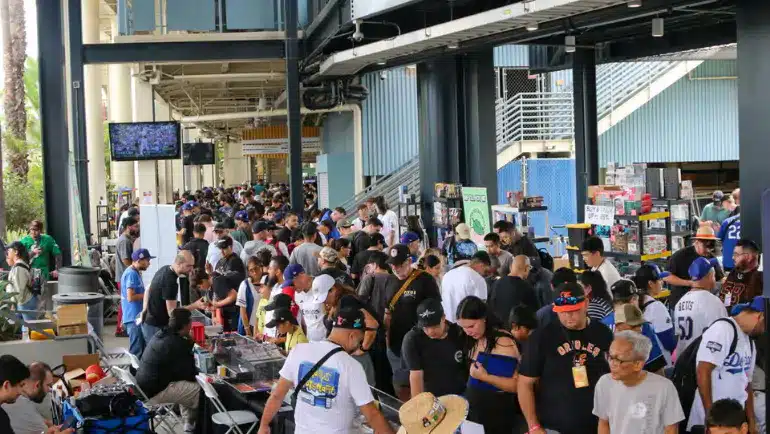
Mobile payment options for businesses selling at conventions, trade shows and other temporary locations.
Payments for stores selling board games, tabletop products, miniatures, collectibles, accessories and other hobby merchandise.
Processing for sellers of cards, memorabilia, comics and other collectibles where higher-ticket and online sales may play a part.
Processing for eligible live and online sellers. Setup depends on how the break or live sale operates and the processor’s requirements.
Different business models need different payment conversations. That is why the business comes before the application.
We do not begin with: “Which terminal should we ship?”
We begin with: “How does your shop actually sell?”
| What We Review | Why It Matters |
|---|---|
| Products and inventory mix | Helps us understand the business and expected transaction profile |
| In-store vs. online sales | Shows the mix of card-present and CNP activity |
| Monthly processing volume | Helps structure the account around normal sales |
| Peak volume | Product drops, shows and releases can create meaningful spikes |
| Average and maximum ticket | High-value items may need additional consideration |
| Current POS and gateway | Helps determine what can remain in the existing setup |
| Ecommerce channels | Shows how customers pay outside the store |
| Card-show and event sales | Identifies mobile and temporary-location payment needs |
| Chargeback history | Helps identify patterns that may affect the account |
| Fraud exposure | Helps determine which controls may be appropriate |
| Growth plans | Helps build around where the shop is going next |
| Only then do we recommend the payment setup. | |
A card shop is not just a cash register with Pokémon behind it.
The same business may sell a $4 booster pack, a $500 hobby box and a $5,000 slab.
It may sell across the counter today and from a convention table tomorrow.
USA Payments looks at that transaction mix before recommending the payment setup.
The processor should understand the business it is processing for.
High-value and card‑not‑present sales deserve more attention than simply whether the transaction receives an approval code.
Depending on the setup, USA Payments can help evaluate fraud-prevention and chargeback-management tools designed to give the shop more information before and after a transaction.
Some card shops need a straightforward terminal.
Others already run a specialized POS, ecommerce system or shop-management platform.
USA Payments reviews what the business already uses before recommending a change.
Where the current technology can work with an appropriate payment setup, there is no reason to replace it simply to create more work.
Where a different setup would solve a real problem, we can evaluate the options.
Card businesses move quickly.
A high-value sale comes through
The shop adds ecommerce
A big event is coming
Volume changes
A processor asks a question
USA Payments gives the business a human point of contact who can understand what changed and help determine what happens next.
You should not have to explain what a card break is to a generic support queue every time you need help.
Not automatically.
How a card or hobby shop is evaluated can depend on factors such as transaction size, online sales, card-not-present volume, chargeback history, products sold and overall processing profile.
A local shop processing mostly lower-ticket card-present transactions may look very different from a business selling high-value collectibles primarily online.
USA Payments reviews the actual business rather than assuming every card shop fits the same risk category.
Potentially.
If high-value transactions are normal for the business, the processing account should be structured with those ticket sizes in mind.
USA Payments reviews average and maximum transaction amounts before recommending a setup.
For certain larger sales, ACH or Pay by Bank may also be worth evaluating.
Yes, when supported by the processor and payment setup.
Online transactions generally fall into the card-not-present environment and can carry different fraud, chargeback and pricing considerations from in-store transactions.
USA Payments can evaluate online processing alongside the shop’s card-present setup.
Potentially.
Mobile terminals and other supported payment options can allow card and hobby businesses to accept card-present payments at shows, conventions and other events.
The right setup depends on how and where the business sells.
Potentially.
The answer depends on how the business operates, what is being sold, how customers purchase into the sale and the processor’s underwriting requirements.
USA Payments reviews the actual business model before determining which processing options may be available.
We do not assume every breaking or live-selling operation should be treated the same way.
Often, but compatibility depends on the software, gateway and processor.
USA Payments reviews the existing system before recommending unnecessary changes.
If your current POS or ecommerce platform can work with an appropriate payment solution, keeping it may make more sense.
Marketplaces generally control the checkout and payment processing that happens inside their platforms.
USA Payments focuses on payment channels the card or hobby business controls, such as its physical store, owned website, events and other supported direct-payment channels.
Many shops use both marketplace sales and their own payment infrastructure.
Potentially.
Bank-based payment options may be worth evaluating for certain larger transactions or business relationships.
Whether ACH or Pay by Bank is appropriate depends on the sale and customer experience.
USA Payments can help businesses evaluate fraud-prevention and chargeback-management tools as part of the payment setup.
No tool can eliminate fraud or guarantee that a dispute will always be won.
The objective is to give the shop better controls and better information around higher-risk transactions.
Your payments should be ready for the $5 sale, the $5,000 sale and the weekend when everyone wants the same new release.
USA Payments will review:
If the current setup fits the business, we will tell you.
If there is a stronger way to structure it, we will show you where the opportunity is.